Maria went freelance three years ago, shooting weddings and portraits around Denver. When she set up her first retirement account, her accountant at the time recommended a SEP IRA — simple to open, one form, done. She's contributed to it every year since. Nobody ever suggested she reconsider.
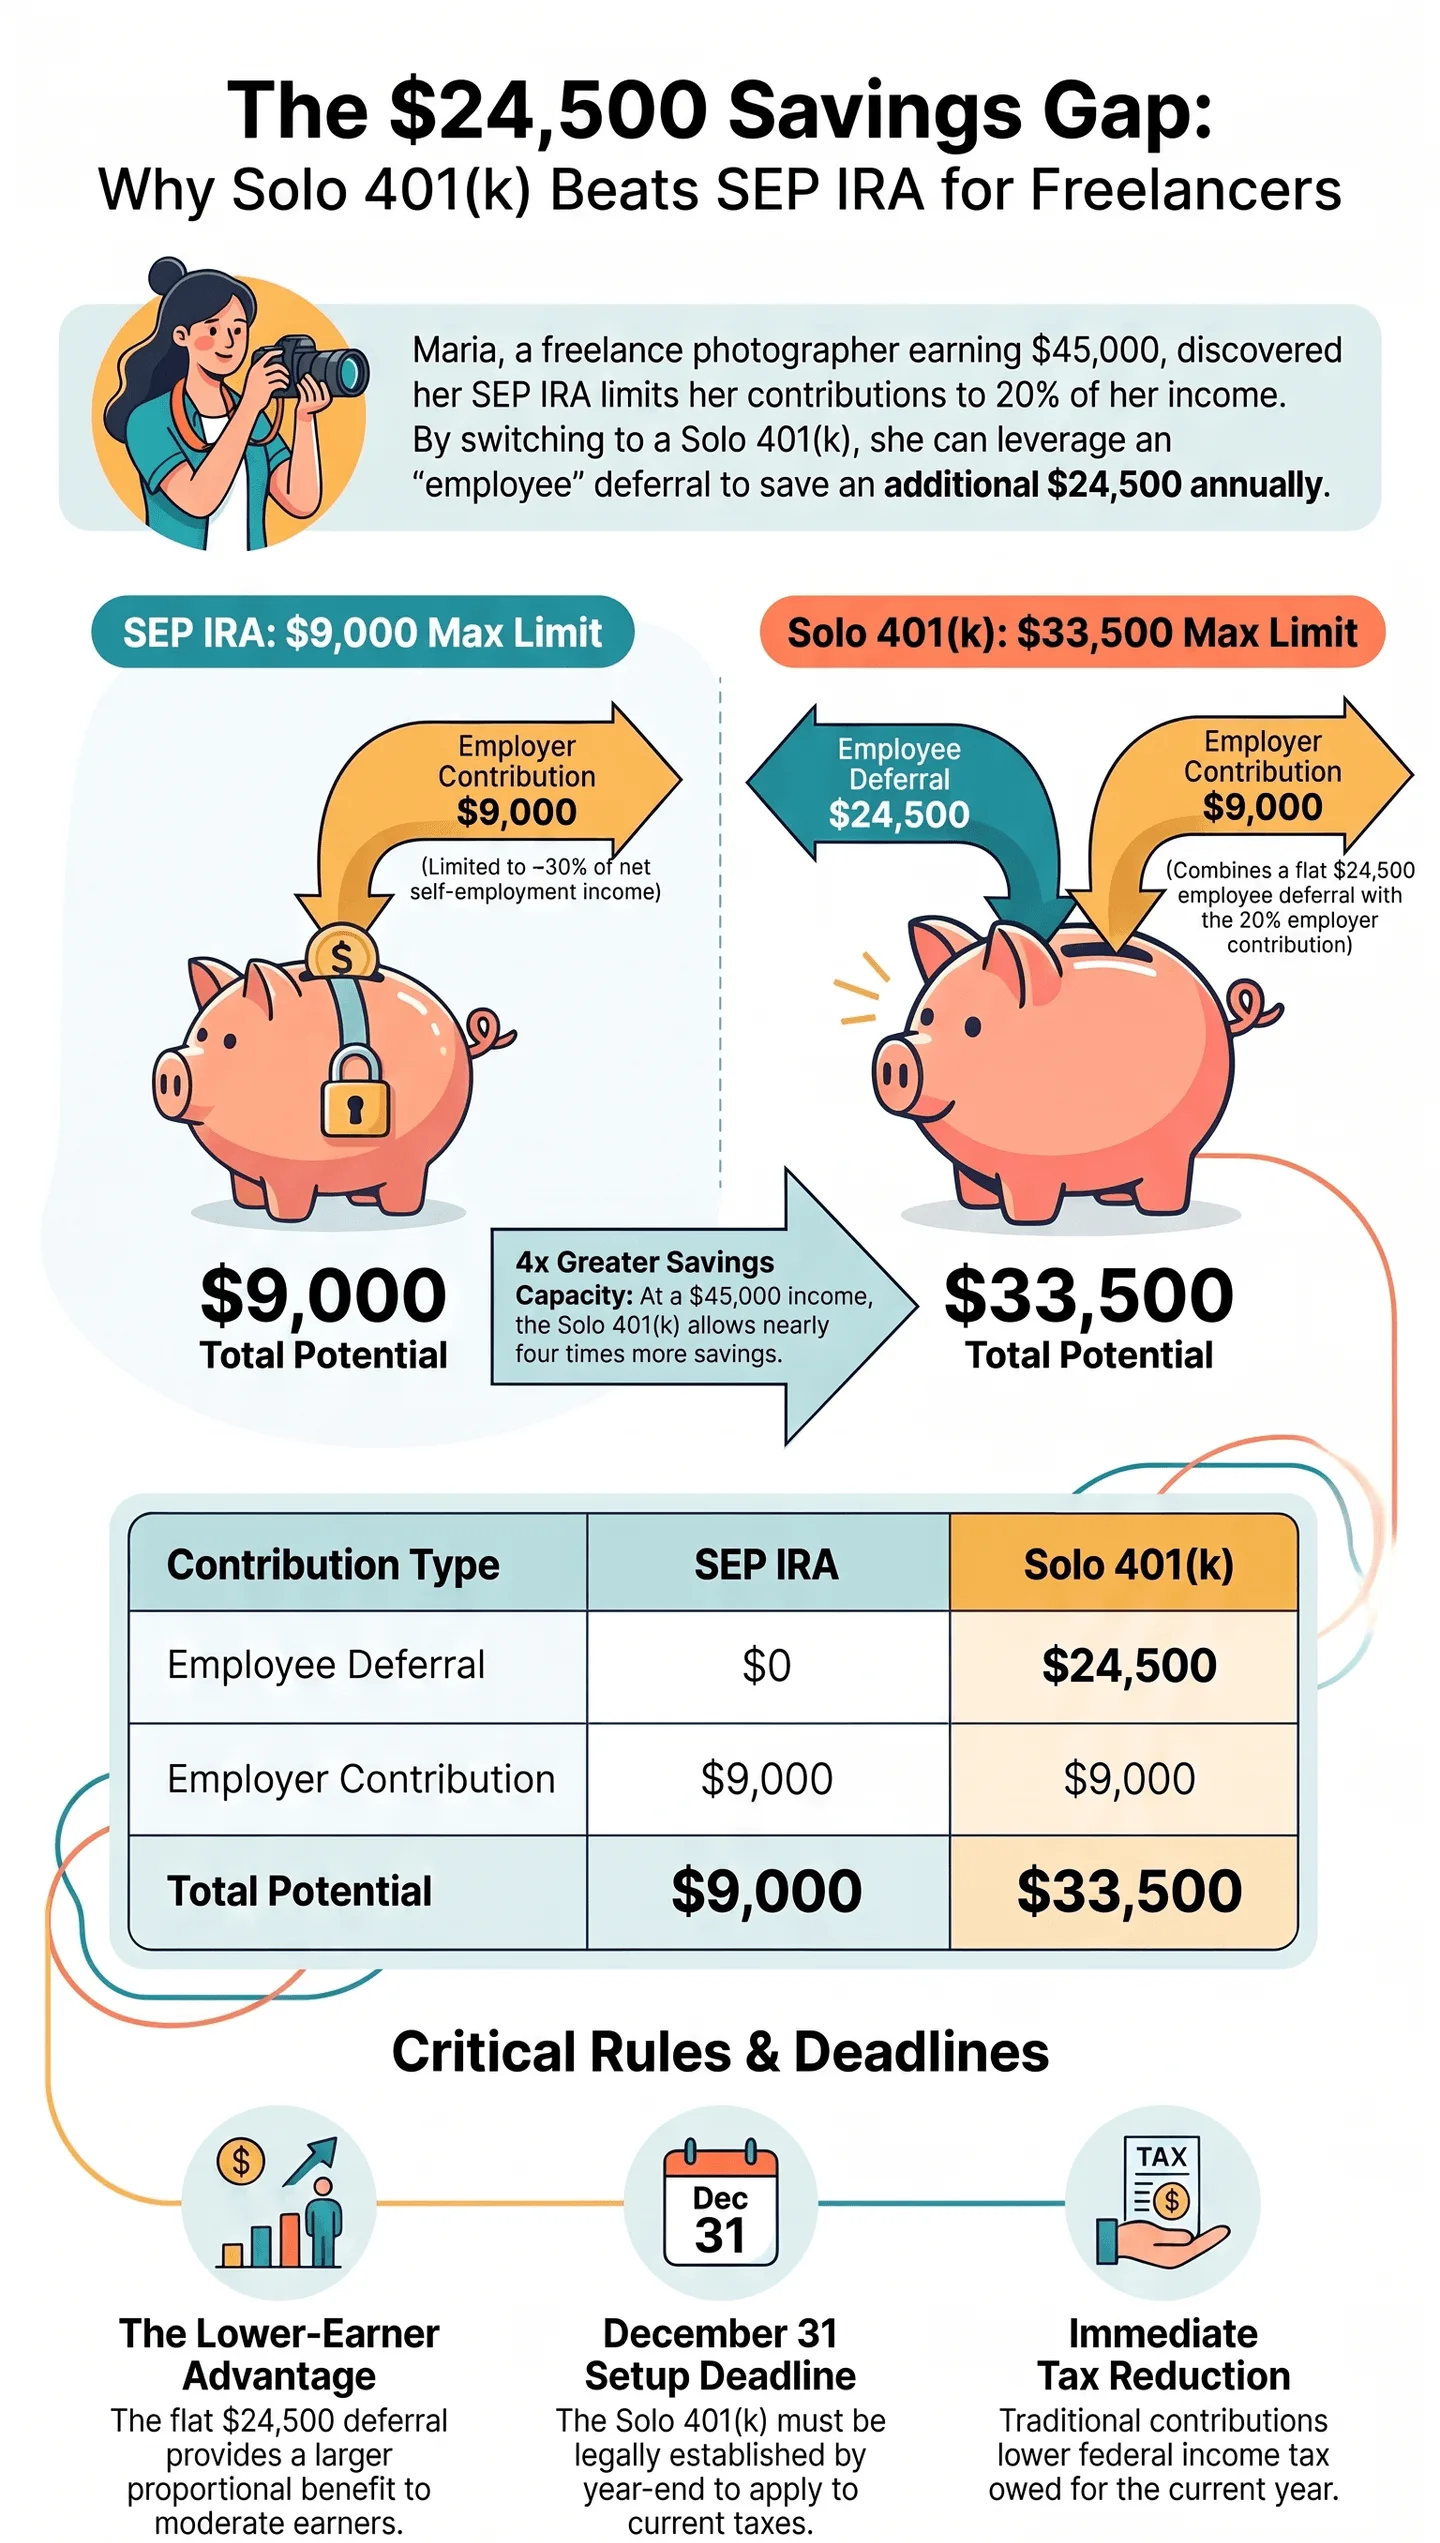
This year, her net self-employment income landed at $45,000. When she ran her numbers through a retirement calculator out of curiosity, she found out her SEP IRA has been quietly limiting her to about half of what she could actually be saving — and the fix is more straightforward than she expected.
What Maria's SEP IRA Actually Allows
A SEP IRA is an employer-only contribution — there's no separate "employee" bucket to defer income into, which is the piece most self-employed people don't realize when they set one up. The contribution formula for a sole proprietor comes out to roughly 20% of net self-employment income, after adjusting for self-employment tax.
At Maria's $45,000 in net income: $45,000 × 20% = $9,000 maximum SEP IRA contribution for the year.
What a Solo 401(k) Would Allow at the Same Income
A Solo 401(k) works differently because it lets Maria contribute in two separate roles — as the "employee" and as the "employer" — even though she's a one-person business.
- Employee deferral: Up to $24,500 for 2026, and this amount doesn't depend on her income level at all — it's a flat dollar limit available to anyone with enough net earnings to support it
- Employer contribution: The same ~20% formula as the SEP IRA, applied to her $45,000 income: another $9,000
Combined: $24,500 + $9,000 = $33,500 — nearly four times what the SEP IRA alone allows.
The Gap, In Real Numbers
| SEP IRA | Solo 401(k) | |
|---|---|---|
| Employee deferral | Not available | $24,500 |
| Employer contribution (~20%) | $9,000 | $9,000 |
| Total | $9,000 | $33,500 |
That's a $24,500 difference — money Maria could be setting aside for retirement every year at her current income level, simply by using a different type of account with the same underlying self-employment income.
Why This Gap Is Bigger for Lower Earners, Not Smaller
It might seem counterintuitive that someone earning $45,000 sees a bigger proportional gap than someone earning $150,000 — but the math works that way because the Solo 401(k)'s employee deferral is a flat $24,500 regardless of income, while the employer-side contribution scales with earnings either way. At lower income levels, that flat deferral amount represents a much larger share of what someone could otherwise save, which is exactly Maria's situation.
The Tax Impact, Not Just the Retirement Impact
Beyond the extra $24,500 in savings capacity, this also reduces Maria's current-year taxable income if she contributes on a traditional (pre-tax) basis — at her income level, this could mean a few thousand dollars less in federal income tax owed this year, on top of the long-term retirement benefit. The exact amount depends on her full tax picture, which is why running her specific numbers through a calculator matters more than a generic percentage.
What Maria Needs to Do Before December 31
The one detail that actually creates urgency: a Solo 401(k) has to be legally established by December 31 of the tax year, even though the money itself can be contributed later, up to the tax filing deadline. If Maria wants this switch to apply to this year's taxes rather than waiting until next year, she needs to open the account — not necessarily fund it yet — before the calendar turns over. A SEP IRA doesn't have this same year-end deadline, which is part of why it's the "easier" default that many freelancers never revisit.
See Your Own Numbers
Maria's situation — sole proprietor, moderate income, been using the "simple" retirement option without knowing there was a much larger one available — is common enough that it's worth checking your own numbers directly rather than assuming your SEP IRA is fine because it was fine when you set it up. Run your actual net income through our Solo 401(k) vs SEP IRA Calculator to see your specific gap.
Frequently Asked Questions
Can Maria actually afford to contribute $33,500 out of $45,000 in income?
Probably not, and the limit is a ceiling rather than a target. The point of the comparison is that the SEP IRA caps her at $9,000 whether or not she has more to save — so in a good year, or a year with a large client payment, the SEP IRA is the thing standing in her way. The Solo 401(k) costs nothing extra to hold at a lower contribution level, which is what makes the switch worth making before she needs the extra room rather than after.
Does she have to contribute the same amount every year?
No. Both accounts allow contributing whatever she wants up to the limit, including nothing at all in a lean year. This is a common misunderstanding that keeps freelancers in a SEP IRA — there is no minimum, no penalty for skipping a year, and no obligation created by opening the account.
Is a Solo 401(k) harder to administer than a SEP IRA?
Slightly, but less than its reputation suggests. The real difference appears once the account balance passes $250,000, at which point the IRS requires an annual Form 5500-EZ filing. Below that threshold there is no annual return to file. Most providers that offer Solo 401(k)s handle the plan documents themselves at no cost, so the practical extra work in Maria's first years is close to zero.
Can she contribute to a Roth Solo 401(k) instead?
Yes, and at Maria's income it deserves a look. The $24,500 employee deferral can go in as Roth — taxed now, withdrawn tax-free later — while the employer contribution has historically been pre-tax only. At $45,000 of income she is in a relatively low bracket, so paying tax on the contribution now can cost less than paying it on the withdrawals decades from now. This trade-off runs the opposite way for high earners, which is why the answer is not the same for everyone.
What happens to her existing SEP IRA if she switches?
It stays where it is unless she moves it. She can leave the balance in place and simply stop contributing to it, or roll it into the new Solo 401(k) as a direct trustee-to-trustee transfer. Rolling it over does not use up any of her contribution room for the year, and it leaves no pre-tax IRA balance behind — which matters if she ever wants to use a backdoor Roth IRA, since a leftover SEP balance would trigger the pro-rata rule.